
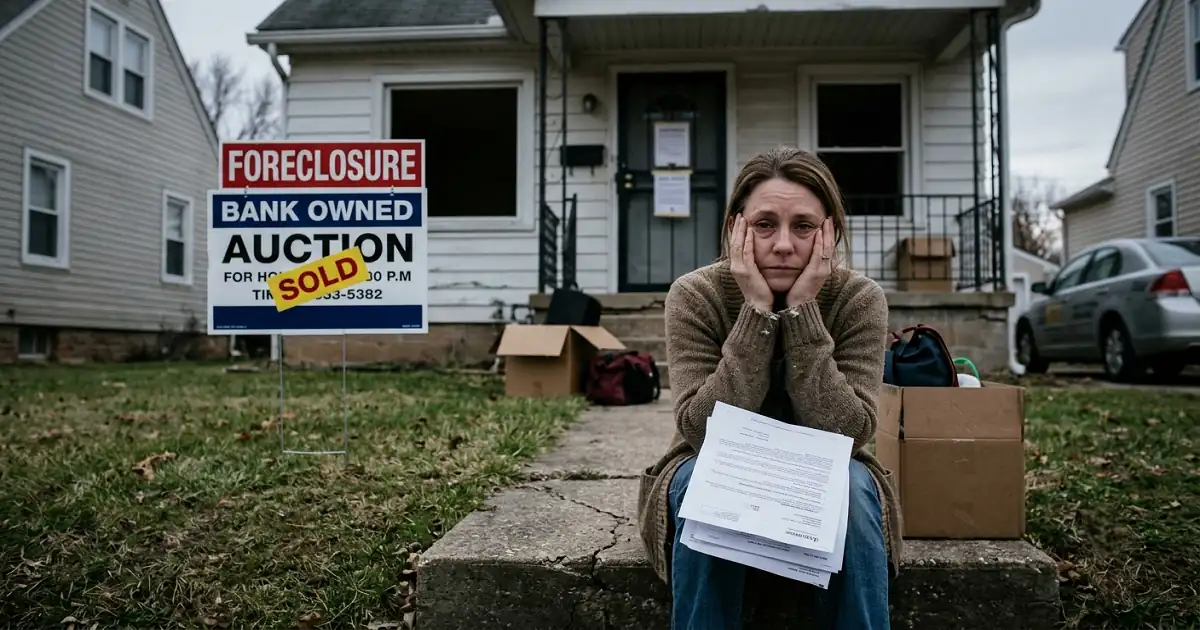
She had moved into a rental in Middleburg and was starting to feel almost normal again. The house had sold at auction in March and she had made herself stop thinking about it.
Then in October a letter came from a law firm she had never heard of, with a number on it: eighty one thousand dollars.
The first thing she said to me on the phone was that she thought it was finished. The second thing she said was that she did not know you could still owe money on a house you no longer own.
On a Florida homestead, they generally have one year, and the number is capped at what the house was actually worth.
Two protections most people have never heard of, and one trap that catches the people who thought they chose the safer exit.
I’m Kady. I help Florida homeowners through foreclosure, hardship, inherited property, illness, divorce, and everything else that arrives in a pile. I am a Realtor with Momentum Realty and I buy houses.
Almost everything written about foreclosure is about stopping it. I have written a lot of it myself. But a certain number of people lose the house anyway, and then they live for years with a question nobody ever answered for them, which is whether somebody is going to turn up one day and ask for the difference.
So this is the page about afterwards. What a deficiency judgment is, the two Florida protections that work in your favour, the one real trap, what they can actually collect if one is entered, and when you can buy a house again.
Most of it is better news than people expect. Some of it is not. All of it is the sort of thing you want to know before you choose between a short sale and a deed in lieu, which is why I have put the trap in section 04 rather than burying it.
A deficiency is the gap between what you owed and what the house brought. Florida gives you two significant protections on an owner occupied home. Under section 702.06 the deficiency on owner occupied residential property is capped at the judgment amount less the property’s fair market value on the sale date, and owner occupancy is presumed if the property carried a homestead exemption on the last certified assessment before the foreclosure was filed. And under section 95.11(6)(g) the lender has one year for residential property of one to four units, running from the day after the clerk issues the certificate of title, or the day after the lender accepts a deed in lieu. Miss it and the claim is permanently barred. The trap: a short sale does not appear in that limitation statute, so the general five year period applies instead. Rentals, second homes and commercial property fall outside the fair market value cap entirely. And if a deficiency is entered, Florida’s homestead protection and the head of household exemption at section 222.11 limit what can actually be collected.
- It is not automatic. The lender has to ask, and prove the house was worth less than the debt.
- One year on a Florida residential foreclosure or deed in lieu, from the day after title issues.
- Five years after a short sale, which is the opposite of what everyone assumes.
- The number is capped at the judgment less fair market value, on an owner occupied home.
- Homestead and head of household protect a great deal even if a judgment exists.
- Do not ignore a lawsuit. A default judgment hands them everything the defences would have limited.
01What A Deficiency Judgment Actually Is
Simple arithmetic with a frightening name.
You owed $310,000 on the judgment. The house sold at the auction for $229,000. The gap is $81,000, and a deficiency judgment is a court order saying you personally owe that gap as an ordinary debt.
Four things about it that people get wrong.
It is not automatic. Losing the house does not create a deficiency judgment. The lender has to go and ask for one, by motion in the foreclosure case or in a separate suit, and it has to prove the fair market value was below the outstanding balance. Plenty of lenders never bother, particularly where the borrower has nothing worth collecting.
It is a personal debt, not a property debt. Once entered it behaves like any other money judgment. It can be collected against, it accrues interest, and it can be sold to a debt buyer, which is why the letter often arrives from a company you have never heard of.
It is not the same as what you owed. On an owner occupied Florida home the amount is capped, which is the next section and the best news on this page.
And there is a clock. A short one on residential property, which is section 03.
02The Cap That Protects Florida Homesteads
Florida Statutes section 702.06 does something genuinely protective, and almost nobody facing this knows it exists.
On owner occupied residential property, the deficiency is capped at the judgment amount less the fair market value of the property on the date of the sale. Not less the auction price. Less what the house was actually worth.
That distinction matters enormously, because foreclosure auctions routinely produce prices well below market value. If your judgment was $310,000 and the house sold for $229,000 but was genuinely worth $285,000 on that day, the cap measures against the $285,000, not the $229,000. The gap they can pursue shrinks from $81,000 to $25,000.
And if a third party bids above fair market value, the deficiency is the judgment less the sale price, whichever figure produces the smaller deficiency. The cap works in your favour both ways.
How do you establish owner occupancy? You usually do not have to. If the property carried a homestead exemption on the most recent certified assessment before the foreclosure was filed, owner occupancy is presumed. Either side can rebut that presumption, but the starting position favours you.
Which gives you one very practical instruction. If you are reading this and you still own the home, go and confirm your homestead exemption is on the roll. People let it lapse after a death, after a move, after a divorce, or they simply never filed. That exemption is doing more work than almost anything else you own.
And the flip side, stated plainly because it catches investors and second home owners. Rentals, second homes and commercial property are outside this cap. There the deficiency is the full debt less the auction price, which is exactly the scenario where these numbers get large.
03The One Year Clock
Here is the second protection, and it is the one that has quietly ended a great many of these claims.
Under section 95.11(6)(g), for residential property of one to four units, an action to seek a deficiency must be brought within one year. The clock starts the day after the clerk issues the certificate of title, or the day after the lender accepts a deed in lieu.
Miss it and the claim is permanently barred. Not reduced. Barred.
Two refinements worth knowing because they come up.
It applies inside the foreclosure case too. Lenders have argued that the one year limit only governs a separate suit, and that a motion within the existing foreclosure case escapes it. In Accardi v. Regions Bank that argument did not succeed; the limit was applied to the motion as well.
A reservation of jurisdiction does not decide anything. Foreclosure judgments routinely contain wording reserving jurisdiction to consider a deficiency later. Under Dyck-O’Neal, Inc. v. Lanham, a separate deficiency suit is barred only once the foreclosure court has actually granted or denied a deficiency claim. A mere reservation is not a decision. So if your judgment contains that wording, it does not by itself mean a deficiency is coming, and it does not by itself mean one is foreclosed.
So the practical question for anybody who lost a Florida home is simple and answerable. When did the certificate of title issue? Look it up on your county clerk’s docket, which is free. Add one year. If that date has passed and nothing was filed, the position is very different from what the letter in your hand suggests. Take that date to a Florida attorney rather than to the debt collector.
04The Short Sale Trap
Now the part that genuinely surprised me when I went and read it properly, and the reason I think this page needs to exist.
Almost everybody believes a short sale is the gentler, safer exit and a deed in lieu is the rougher one. On the deficiency clock, it is the other way round.
| How it ended | Limitation period | Clock starts |
|---|---|---|
| Foreclosure sale, residential 1 to 4 units | 1 year | Day after the clerk issues the certificate of title |
| Deed in lieu, residential | 1 year | Day after the lender accepts the deed in lieu |
| Short sale | 5 years | Short sales do not appear in the limitation statute, so the general period for written contracts applies |
| Commercial property or a vehicle loan | 5 years | General period for written contracts |
Short sales simply are not named in the one year provision, and the appellate decisions in Bush v. Whitney Bank and Whitney Bank v. Grant hold that a short sale does not start that one year clock. So the longer five year period applies.
Read what that means. Choose a deed in lieu and your exposure window closes in twelve months. Choose a short sale and it stays open for five years.
This does not mean short sales are bad
I want to be careful here, because this is one factor among several and I am not an attorney. A short sale can be better than a deed in lieu for other reasons, including the mortgage waiting period afterwards, how the lender reports it, and what your situation actually allows. And a short sale approval can be negotiated to include a release of the deficiency, which removes the issue altogether. That is the single most important thing to ask for, in writing, before you agree to anything. What the limitation point means is that the deficiency release matters far more on a short sale than people realise, because without one the window stays open five times longer. Take this to a Florida real estate attorney before you choose between the two, and get the release language reviewed.
I have written about both exits in context in the foreclosure process in Florida, and about the sale route that avoids this question entirely in selling a house as is for cash in Florida. A sale that pays the debt in full creates no deficiency at all, which is the cleanest version of this whole conversation.
05If One Is Entered, What Can They Take?
Less than you fear, if you are a Florida resident, and this is where the state’s reputation is earned.
Your new homestead is protected. Florida’s constitutional homestead protection shields your primary residence from most judgment creditors, with exceptions including mortgages, taxes and mechanics liens. A deficiency judgment creditor cannot generally force the sale of a Florida homestead. People who lost one house and later bought another are frequently far safer than they assume.
Your wages may be entirely exempt. This is the one almost nobody knows. Under section 222.11, a debtor who qualifies as head of household, meaning they provide more than half the financial support for a child or other dependent, has their disposable earnings protected. If disposable earnings are $750 a week or less, they are fully exempt and that protection cannot be waived. Above $750 a week they are still exempt unless the debtor signed a valid written waiver, and even then garnishment is capped at the federal limit.
The dependent does not have to be a minor child. An adult child, a non working spouse, an elderly parent or anybody you genuinely support more than half of can qualify you. The test is actual support, not whether you claim them on a tax return.
The 20 day deadline if your wages are garnished
The head of household exemption is not automatic. You have to claim it. After a writ of garnishment is served you file a Claim of Exemption and Request for Hearing with the clerk within 20 days of receiving the writ and form, have it notarised, and send copies to the creditor or its attorney and to your employer. If the creditor does not object within 8 business days of hand delivery or 14 business days of mailing, the garnishment is dissolved automatically. If they do object, there is a hearing and you have to prove you qualify, with things like tax returns showing dependents, pay stubs, bank statements and household expense records. An affidavit filed before a writ is served has no effect. Twenty days, again. Florida runs on that number.
Two things that are not protected and that I will not pretend otherwise about. Bank accounts are more exposed than wages, although wages deposited into an account may retain their exempt character in some circumstances, which is an attorney question. And child support, alimony, IRS levies and federal obligations can reach earnings that an ordinary creditor cannot.
Also worth raising with a CPA rather than with me: forgiven or cancelled debt can generate a Form 1099-C and may have income tax consequences, though exclusions can apply depending on your circumstances. That is a tax question with real money in it and it is worth one proper conversation rather than a guess.
06When Can You Buy Again?
This is the question underneath the question, and for most people it matters more than the deficiency does.
| Loan type | Event | Standard wait | With documented extenuating circumstances |
|---|---|---|---|
| Conventional | Foreclosure | 7 years | 3 years, with a 90 percent maximum LTV, principal residence or limited cash out refinance |
| Conventional | Deed in lieu or short sale | 4 years | 2 years |
| FHA | Foreclosure | 3 years from title transfer | Potentially 12 months with documented circumstances and re-established credit |
| FHA | Deed in lieu or short sale | 3 years, or none if all mortgage and installment debts were current for the 12 months before | Potentially 12 months |
| VA | Foreclosure | 2 years | Entitlement is a separate question from seasoning |
| VA | Short sale or deed in lieu | Up to 2 years, often none if payments stayed current through the sale | As above |
| USDA | Any of the three | 3 years | Applications inside 36 months need a documented credit exception |
Three observations that matter more than the table.
The clock starts at completion, when title transferred. Not when you stopped paying, not when you moved out. So the certificate of title date you looked up in section 03 is doing double duty: it sets your deficiency window and it sets your waiting period.
A deed in lieu or short sale beats a foreclosure substantially here. Four years against seven on conventional. That is a real reason to pursue one even when it feels like the same outcome, and it is the other side of the ledger from the limitation point in section 04. Neither consideration decides it alone.
Veterans have a separate issue. If the home you lost was financed with a VA loan, a claim paid on that foreclosure comes out of your entitlement, and that is a distinct question from the seasoning period. Ask the VA directly on 877-827-3702 about your own entitlement position. More on that in behind on a VA loan in Florida.
07Surplus Funds, And Getting Out Of The House
Two practical things that sit on the other side of a foreclosure and that people miss.
Surplus funds. If the property sold for more than the judgment amount, the surplus belongs to the former owner, subject to the claims of subordinate lienholders, and it has to be claimed through the clerk. People genuinely walk away from money they are owed because nobody told them it existed. Check the docket.
Leaving the property. You are the owner until the certificate of title issues. After that, the new owner obtains a writ of possession through the clerk and the sheriff executes it. How much warning you get varies. This is worth understanding in advance rather than discovering, so that your move is planned rather than performed in forty eight hours with children involved.
And the thing that avoids all of this. A sale that pays the debt in full creates no deficiency, no surplus question and no writ of possession. If there is equity in the house and you are heading toward a judgment, selling it yourself is not a defeat. It is the version where you control the price and the date, keep the difference, protect your credit far better, and never receive the letter the woman in Middleburg received in October.
08What This Should Change
If you still have a choice to make, four things on this page should change how you make it.
Confirm your homestead exemption. It drives the presumption of owner occupancy that brings you inside the section 702.06 cap. It is probably the single highest value piece of paperwork you own and it takes one call to the property appraiser.
If you are weighing a short sale against a deed in lieu, get the deficiency release in writing. On a deed in lieu the exposure window closes in a year anyway. On a short sale it stays open for five unless the approval releases you. Ask for the release, read the approval letter, and have an attorney read it too.
If there is equity, sell before judgment. No deficiency arises where the debt is paid, and you keep the difference rather than handing it to the process.
If a deficiency suit arrives, do not ignore it. A default judgment hands them the whole amount with none of the limits in this article applied, because nobody raised them. The cap is a defence. The limitation period is a defence. Defences only work if somebody makes them.
What people believe
They took the house, so the debt is settled and it is over.
What is true
A deficiency can still be pursued, but it is not automatic, it is capped on an owner occupied home, and the clock is short.
What people believe
A short sale is the safer choice because it is not a foreclosure.
What is true
On the deficiency clock a short sale leaves five years open against one for a deed in lieu, unless the approval releases the deficiency.
What people believe
If they get a judgment they will take my wages and my new house.
What is true
Florida homestead protection and the head of household exemption at 222.11 shield a great deal, but you have to claim the exemption within 20 days.
The woman in Middleburg took her letter to an attorney, which is what I told her to do and about the limit of what I am qualified to say.
What I could do was help her find the date the certificate of title issued, which took about four minutes on the clerk’s website and which neither she nor the person who wrote to her had mentioned.
I am not going to tell you how that ended, because it is hers. I will tell you that the date mattered, and that she had been carrying that number around for seven months without knowing there was a question to ask.
Four minutes. That is the whole reason I wrote this one.
If a letter has already arrived
Four things, in this order, and none of them is paying it. Do not acknowledge the debt or agree to anything on the phone, because in some circumstances that can affect your position. Find the certificate of title date on your county clerk’s docket, free, and work out whether a year has passed. Check what kind of property it was, because the section 702.06 cap applies to owner occupied residential and not to rentals, second homes or commercial. And take all of it to a Florida attorney, including the letter and the dates. Many will look at a deficiency letter for a modest fee or a free first call, and legal aid serves qualifying households. What you must not do is ignore a filed lawsuit, because a default judgment applies none of these protections.
It is not automatic. One year on a foreclosure or deed in lieu. Five on a short sale without a release. The amount is capped on an owner occupied home. Claim the exemption within 20 days.
If you are weighing a short sale against a deed in lieu, or wondering whether selling before judgment is possible, tell me the numbers and I will tell you honestly what I would do, including when the answer is an attorney and not me.
Questions People Ask Me
Can a lender come after me after foreclosure in Florida?
They can seek a deficiency judgment, but it is not automatic. The lender has to file a motion in the foreclosure case or a separate suit and prove the property’s fair market value was below the outstanding balance. On owner occupied residential property the amount is capped under section 702.06 at the judgment amount less the fair market value on the sale date, and for residential property of one to four units the claim must be brought within one year under section 95.11(6)(g). Many lenders never pursue one, particularly where there is nothing worth collecting.
How long does a lender have to seek a deficiency in Florida?
For residential property of one to four units, one year. The clock starts the day after the clerk issues the certificate of title, or the day after the lender accepts a deed in lieu. Missing that deadline permanently bars the claim. In Accardi v. Regions Bank the limit was applied to a motion filed within the foreclosure case, not only to a separate lawsuit. Commercial property and vehicle loans fall under the general five year period for written contracts.
How is the deficiency amount calculated?
On owner occupied residential property, section 702.06 caps it at the judgment amount less the property’s fair market value on the date of sale. That is important because auctions frequently produce prices well below market value, and the cap measures against value rather than the auction price. If a third party bids above fair market value, the deficiency is the judgment less the sale price, whichever produces the smaller figure. Rentals, second homes and commercial property fall outside the cap entirely, so there the deficiency is the full debt less the auction price.
How do I prove the house was my primary residence?
Usually you do not have to. Owner occupancy is presumed if the property carried a homestead exemption on the latest certified assessment roll before the foreclosure action was filed. The presumption is rebuttable by either side, but the starting position favours the homeowner. This is one more reason to make sure your homestead exemption is actually on the roll, since people let it lapse after a death, a move or a divorce, or never filed in the first place.
Is a short sale safer than a deed in lieu?
Not on the deficiency clock, and this surprises almost everyone. A deed in lieu starts the one year limitation period the day after the lender accepts it. A short sale does not appear in the limitation statute at all, so under Bush v. Whitney Bank and Whitney Bank v. Grant the general five year period applies. That said, a short sale may be better for other reasons including the mortgage waiting period afterwards, and a short sale approval can be negotiated to include a release of the deficiency, which removes the issue. Get that release in writing and have an attorney read it.
What is a deficiency release and why does it matter?
It is language in a short sale approval or settlement under which the lender gives up its right to pursue you for the shortfall. It matters most on a short sale, precisely because without one the exposure window runs five years rather than one. Ask for it specifically and in writing before agreeing to anything, read the approval letter carefully rather than skimming it, and have a Florida real estate attorney review the wording. It is the single most valuable thing to negotiate in a short sale.
Can they take my wages?
Often not, if you qualify as head of household under section 222.11, meaning you provide more than half the financial support for a child or other dependent. If your disposable earnings are $750 a week or less they are fully exempt and that protection cannot be waived. Above $750 a week they remain exempt unless you signed a valid written waiver, and even then garnishment is capped at the federal limit. The dependent need not be a minor child; an adult child, a non working spouse or an elderly parent can qualify you, and the test is actual support rather than tax dependency.
How do I claim the head of household exemption?
It is not automatic. After a writ of garnishment is served you file a Claim of Exemption and Request for Hearing with the clerk within 20 days of receiving the writ and form, have it notarised, and send copies to the creditor or its attorney and to your employer. If the creditor does not object within 8 business days of hand delivery or 14 business days of mailing, the garnishment is dissolved automatically. If they object there is a hearing and you must prove you qualify, using tax returns showing dependents, pay stubs, bank statements and household expense records. An affidavit filed before a writ is served has no effect.
Can they take my new house?
Generally not, if it is your Florida homestead. Florida’s constitutional homestead protection shields a primary residence from most judgment creditors, with exceptions including mortgages, taxes and mechanics liens. A deficiency judgment creditor cannot generally force the sale of a Florida homestead. People who lost one house and later bought another in Florida are frequently in a much stronger position than they assume, though the specifics are worth confirming with an attorney.
Who is the law firm that wrote to me? I have never heard of them.
A deficiency judgment, once entered, behaves like any other money judgment, which means it can be sold. Debt buyers purchase these and then pursue them, which is why the letter often comes from a company with no connection to your original lender. That does not make the claim invalid, and it does not make it valid either. Do not acknowledge the debt or agree to anything on the phone. Find the certificate of title date, work out whether the limitation period has run, and take the letter to an attorney.
What if I ignore it?
That is the worst available option. If a lawsuit has been filed and you do not respond, a default judgment can be entered for the full amount with none of the protections in this article applied, because nobody raised them. The fair market value cap is a defence. The limitation period is a defence. Defences only operate if somebody makes them, and a default judgment is the one outcome where every protection Florida gives you goes unused.
When can I buy a house again after a foreclosure?
Measured from the completion date when title transferred. Conventional is typically 7 years after a foreclosure, reduced to 3 with documented extenuating circumstances subject to a 90 percent maximum LTV, and 4 years after a deed in lieu or short sale, reduced to 2. FHA is typically 3 years from title transfer, potentially 12 months with documented circumstances and re-established credit. VA is commonly around 2 years, with entitlement a separate question from seasoning. USDA is typically 3 years. Guidelines change and lenders add overlays, so confirm with a lender for your file.
Does a deed in lieu help with the waiting period?
Substantially, on conventional financing. A deed in lieu or short sale typically carries a four year wait against seven for a foreclosure, and two years against three with documented extenuating circumstances. That is a real argument for pursuing one even when it feels like the same outcome. It sits on the other side of the ledger from the limitation point, since a deed in lieu also closes your deficiency window in a year, so on that measure the two considerations point the same way.
What about taxes on forgiven debt?
Cancelled or forgiven debt can generate a Form 1099-C and may have income tax consequences, with various exclusions potentially applying depending on your circumstances. This is genuinely a question for a CPA or tax attorney rather than for a Realtor or a web page, and it is worth one proper conversation rather than a guess, because the sums involved can be meaningful. Raise it before you agree to a short sale or a settlement, not afterwards.
Is there a way to avoid this question entirely?
Yes. A sale that pays the debt in full creates no deficiency, no surplus question and no writ of possession. If there is equity in the house and a judgment is coming, selling it yourself is the version where you control the price and the closing date, keep the difference, protect your credit considerably better, and never receive a letter about a shortfall. Florida values have risen enough that a great many people heading toward foreclosure have equity they have not thought about, because they have been looking at the payment rather than the value.
Keep reading
A gentle note: I am a Florida Realtor with Momentum Realty and a home buyer, not an attorney, an accountant or a tax professional, and this is general information rather than advice about your situation. Deficiency law turns on specific dates, the type of property, how the property left your hands and what any settlement or approval actually says, none of which can be assessed from a web page. Statutory and case references here reflect publicly available information as of November 2026, including Florida Statutes sections 702.06, 95.11(6)(g) and 222.11, and the decisions in Accardi v. Regions Bank, Dyck-O’Neal, Inc. v. Lanham, Bush v. Whitney Bank and Whitney Bank v. Grant. Mortgage waiting periods are guideline figures that change and that lenders vary with overlays. Please consult a licensed Florida attorney about a deficiency claim, and a CPA about any tax consequences, before relying on anything here.
Written by Kady Andreoli, founder of Helping Hand Home Solutions FL and a Realtor with Momentum Realty. Helping Florida homeowners explore every available option, from stopping foreclosure to selling on their own terms. Guidance without judgment, and people before profit. 904-400-2131 · kady@helpinghandhomesfl.com