
If you've fallen behind on your mortgage, or you're about to, I know the letters and the phone calls can make you feel like the bank is just circling, waiting to take your home. So let me tell you something that gives a lot of people their first real breath in weeks: your lender does not just guess what to offer you. When you fall behind, there's an actual step-by-step process they're required to walk through first, one designed to help you keep your home if there's any way to make it work. It even has a name. Let's walk through it together, in plain English.
I'm Kady. A lot of what I do is help Florida families who are behind, scared, and not sure what happens next. Understanding this process changes everything, because once you see that there's a real ladder of options, you stop feeling trapped and start feeling like you have a say. And you do.
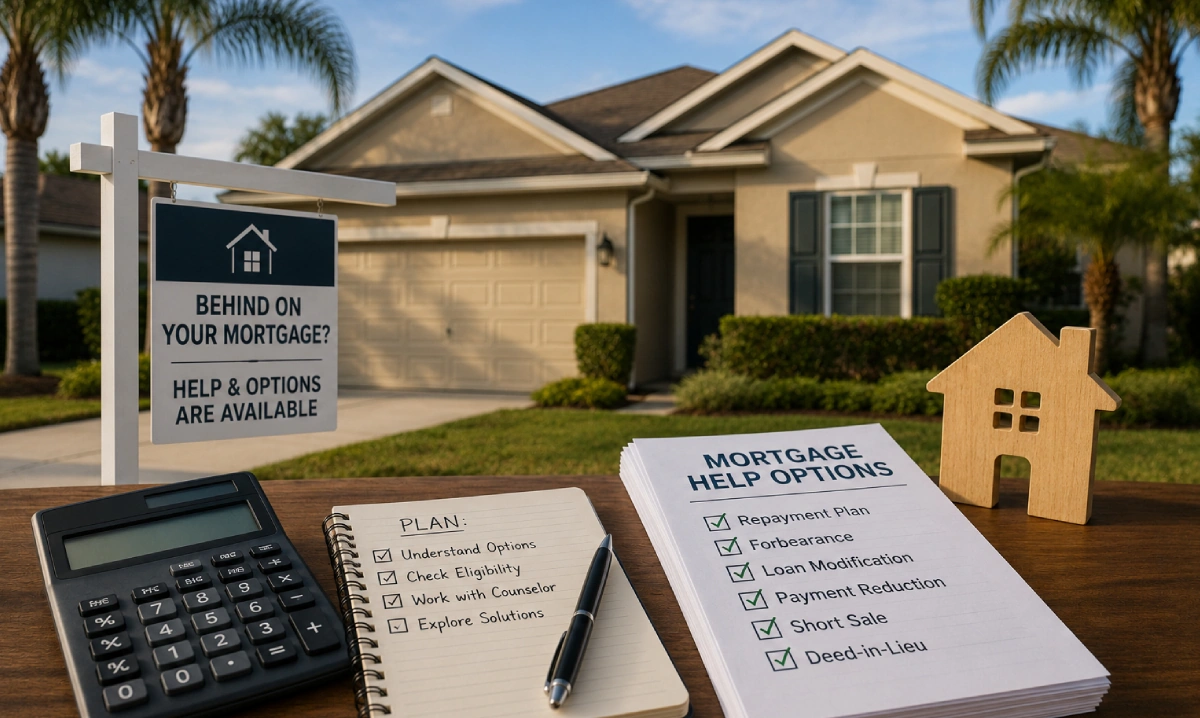
When you fall behind, your lender follows a required order of options called the loss mitigation waterfall (most defined for FHA loans, with similar versions for other loan types). It generally goes: first, early help like a repayment plan or forbearance; then keep-your-home options like a loan modification or partial claim; then deeper relief aimed at cutting your payment by up to 25%; and only if none of that makes the home affordable, home disposition options like a pre-foreclosure (short) sale or deed-in-lieu. As of 2026, the paperwork is lighter than it used to be, and you have the right to be reviewed for all of it. A free HUD-approved housing counselor can guide you, and if selling ends up being your best path, I'm glad to help. The most important thing? Act early.
- Lenders follow a required order, not a guess. It's called the loss mitigation waterfall.
- Keeping your home comes first. The whole early part of the ladder is built to help you stay.
- Deeper relief exists, including options that aim to cut your payment by up to 25%.
- Selling is a real, dignified step, not a punishment, when keeping the home isn't affordable.
- Act early. The sooner you engage, the more rungs of the ladder are still open to you.
01The Bank Isn't Just Guessing
Most people think lenders just decide, almost at random, what to offer when someone falls behind. They don't. Especially with an FHA-insured loan, the servicer has to follow a specific, ordered set of options, and they have to review you for the ones that keep you in your home before they can move toward anything else. That order is what people in my world call the "waterfall," because you move down it one step at a time, only going lower if the step above doesn't solve things.
I love explaining this to people because of what it does to their shoulders. They come in braced for a fight, convinced the bank is the enemy that just wants the house. Then they realize there's a whole structured process designed to help them stay, and you can watch the fear turn into something more like determination. You are not powerless here. You have the right to be walked through every rung.
One honest note before we go further: the clearest, most spelled-out version of this waterfall applies to FHA loans. If you have a different kind of loan (conventional, VA, and so on), your lender follows its own similar playbook of options. The names differ, but the spirit is the same: try to help you keep the home first, and treat selling as a last resort, not a first move.
02The Waterfall, Step by Step
Here's the ladder itself, from the top rung down. Your servicer works through these in order, and the moment one of them actually makes your payment affordable, they stop there. You don't get pushed further down than you need to go.
Repayment plan or forbearance
If your hardship is short-term, the servicer may set up a repayment plan (spreading your past-due amount over your next several payments) or a forbearance (a temporary pause or reduction, often up to 12 months, with special flexibility after a natural disaster). This is the gentlest rung, meant to get you back on your feet without changing your loan.
Loan modification or partial claim
If you can handle your regular payment again but need help catching up the missed amount, a partial claim is an interest-free loan from HUD that brings you current, tucked into a second lien you only repay when you sell or refinance. If you need your payment itself lowered, a loan modification reshapes the loan (often stretched to a 30-year term) to make it affordable. This is the rung Kady's posts call "Step 1."
Combination modification, longer term, or payment supplement
If a standard modification isn't enough, the servicer digs deeper, aiming to cut your principal-and-interest payment by up to 25%. That can mean a combination modification and partial claim, stretching to a 40-year term, or a payment supplement that temporarily lowers your payment for about three years without permanently changing the loan. These are the "Step 2" additional options.
Home disposition: pre-foreclosure sale or deed-in-lieu
If, after all of that, the home simply isn't affordable, the last rung helps you leave without a foreclosure on your record. A pre-foreclosure sale (also called a short sale) lets you sell for less than you owe with the lender's approval, sometimes with relocation help. A deed-in-lieu hands the home back by agreement. This is "Step 3," and it's where selling comes in.
A couple of things worth knowing as you look at that ladder. Before a permanent option locks in, you'll usually complete a short trial payment plan (often three months) to show the new payment works. And you're generally limited to one home-retention option every 24 months, so it's worth getting the right one rather than the fastest one.
Notice how far down the ladder selling is. Three full rungs of help come first, all built to keep you in your home. So if anyone (a stressed-out servicer rep, or that little voice at 3 a.m.) makes you feel like losing the house is a foregone conclusion, it usually isn't. You have real options above that last step, and you have the right to be reviewed for every one of them.
Feeling lost about which rung you're on? That's exactly the kind of thing I can help you sort out, free and with no pressure. Tell me what's happening and I'll help you understand your options. I'm Kady: call or text 904-400-2131, or email kady@helpinghandhomesfl.com.
03Your Rights and What Changed in 2026
The rules around this got friendlier to homeowners, and knowing that can save you a lot of grief. Here's what's true right now:
The paperwork is lighter than it used to be
For a long time, the biggest roadblock was the mountain of financial documents servicers demanded, which caused delays that pushed people closer to foreclosure while they were literally trying to get help. Under the updated framework, your servicer mainly needs to know the reason for your hardship and your occupancy status, and then works with you on what you can afford. Less red tape, faster help.
You have the right to be evaluated for the whole ladder
Your servicer is supposed to review you for the home-retention options before moving toward foreclosure, and in many cases their failure to follow HUD's process can even be a defense against a foreclosure. You are not at their mercy. You have rights baked into this system.
Free, real help exists
A HUD-approved housing counselor can walk you through all of this at no cost to you. They don't work for the bank, they work for you, and they do this every day. I recommend them all the time, right alongside talking with your servicer directly.
Act early, please
This is the one I'll gently repeat: the sooner you engage, the more rungs are still available. Waiting until a foreclosure sale is looming closes doors that were wide open a few months earlier. Even if you're scared to open the letters, making one call early is the most powerful thing you can do.
04Where I Come In
You might be wondering where a home buyer like me fits into all of this. Honestly? Sometimes I don't, and I'll be the first to say so. If a modification or a partial claim lets you keep your home, that's a win, and I'll cheer you on. I'm not here to talk anyone out of staying.
Where I can help is mostly at that bottom rung, and just before it:
- When keeping the home isn't affordable. If you've worked down the ladder and the numbers just don't work, selling before a foreclosure protects your equity and your credit far better than letting it go to auction. I can make a fair, as-is cash offer so you can move on cleanly, on your timeline.
- When you want to sell instead of a short sale or deed-in-lieu. If you have equity, a straightforward sale often leaves you better off than handing the home back. I can help you see whether that's the case.
- When you just need someone to explain it all. Plenty of people call me simply to understand the waterfall and their choices. No obligation. I'll point you toward a counselor or your servicer if that's what serves you best.
If you're weighing whether to keep fighting for the home or let it go, my honest guides on whether you can just walk away from your house and what to do when you can't afford your house anymore both go deeper into the trade-offs.
Someone who came to you behind on payments and terrified, and how it turned out, whether they kept the home through a modification or sold before foreclosure and moved on with relief. A few sentences in your own words will make this whole page feel like you.
"The thing I wish everyone knew is that falling behind isn't the end of the story, it's the start of a process that's actually built to help you. So many people suffer in silence, dodging calls, convinced they've already lost. Then we talk, they see the ladder of options, and something lifts. Whether you keep your home or move on to a fresh start, I just want you to know your choices and feel like a person through all of it, not a case number."
Let's figure out where you stand, together
Tell me what's happening with your mortgage and I'll help you understand your options on the ladder, point you to free help, and, if selling ends up being your best move, get you a fair, no-obligation cash offer.
Get My Cash Offer Just Talk to Kady05Questions People Ask Me
Does my lender really have to follow this order?
For FHA-insured loans, yes, servicers must evaluate you through HUD's ordered loss mitigation options before moving toward foreclosure. Other loan types have their own similar processes. In many cases, a servicer's failure to follow the required steps can even be raised as a defense in a foreclosure, so this structure genuinely protects you.
What's a partial claim, in plain English?
It's an interest-free loan from HUD that covers your past-due amount and brings your mortgage current. It goes into a second lien on your home that you don't make monthly payments on. You only pay it back later, when you sell the home, refinance, or pay off the loan. It's one of the gentler ways to catch up without owing a big lump sum today.
Will a loan modification hurt my credit?
It can have some effect, but it's generally far easier on your credit than missing payment after payment and ending in foreclosure. The whole point of the waterfall is to help you avoid that worst-case outcome. A HUD counselor can walk you through what to expect for your specific situation.
What if none of the keep-your-home options work?
Then you reach the home disposition step, which is designed to help you exit without a foreclosure. That usually means a pre-foreclosure (short) sale or a deed-in-lieu. If you have equity, selling on the open market or to a cash buyer before foreclosure often leaves you better off, because you protect that equity and your credit. That's a spot where I'm glad to help.
How long do I have before it's too late?
More time than it usually feels like, but don't lean on that. Because Florida foreclosures go through the courts, the process takes months, which gives you room to work the ladder. Still, the earlier you act, the more options stay open. Waiting until a sale date is set closes doors, so please reach out early.
Is calling you going to be a hard sales pitch?
No. Honestly, a lot of the time the best thing I can do is point you toward a modification or a free HUD counselor so you can keep your home, and I'm happy to do exactly that. If selling turns out to be your best path, I'll make it simple. Either way, it's a helping hand, not a pitch.
A gentle note: I'm a Florida home buyer, not a lender, mortgage servicer, attorney, or housing counselor, and this article is general information, not legal or financial advice for your situation. Loss mitigation options, especially the FHA waterfall, have specific rules and can change, so please talk with your loan servicer and a free HUD-approved housing counselor about your specific circumstances. And if this is weighing on you, please don't carry it alone. Making one call is the bravest and most helpful first step.
- HUD: FHA's Loss Mitigation Program (home retention and home disposition options)
- HUD: Find a free HUD-approved housing counselor
- HUD Mortgagee Letters 2025-12 and 2025-21, and Handbook 4000.1 (the updated loss mitigation waterfall, effective February 2, 2026)
- FHA Resource Center: 1-800-CALL-FHA (1-800-225-5342)
- Consumer Financial Protection Bureau (CFPB): help for homeowners struggling to pay the mortgage